Why do you need mortgage pre-approval before touring homes in North Texas?

In North Texas, getting pre-approved before you tour homes is the single most important thing you can do to protect your time, your money, and your chances of landing the right house. Fort Worth's market is more balanced in 2026 than it was a few years ago, but homes in attractive price ranges still receive multiple offers, and listing agents routinely set aside offers that don't include a current lender pre-approval letter.

I always tell my clients this before we ever schedule a single showing: the pre-approval isn't paperwork for paperwork's sake. It's the foundation of your entire offer strategy.

What the 2026 Fort Worth Market Actually Looks Like

If you've been watching headlines, you know North Texas has cooled from its pandemic-era intensity. That's true. But "cooled" doesn't mean "easy."

According to the Greater Fort Worth Association of REALTORS® (GFWAR) June 2026 Housing Report, the year-to-date median home price in Fort Worth through the first half of 2026 was $333,068, with the June 2026 median sitting at $335,975, down just 0.3% from June 2025. Tarrant County's year-to-date median was $350,528, and Denton County ran higher at around $434,748. Prices vary meaningfully depending on where you're shopping.

A Fort Worth Report story from July 2026 summarizing the same GFWAR data noted that Q2 2026 saw 1,067 homes sold in June alone, up 5.2% year over year, even as prices softened slightly. That's not a slow market. That's a market with more options for buyers, and still enough demand that being unprepared costs you.

Mid-2026 estimates from Zillow (updated through June 30, 2026) put Fort Worth's median days to pending at around 28 days, with about 21% of homes still closing above list price. Redfin's August 2026 snapshot characterizes Fort Worth as "somewhat competitive," with homes averaging about 2 offers and selling in roughly 46 days. Those two sources use different datasets, so treat them as context rather than definitive figures, but the direction is clear: typical Fort Worth homes go under contract in about one to two months, and multiple offers remain common in well-priced ranges.

The bottom line: you have more negotiating room than buyers had in 2021 or 2022, but you still need to be ready to move when the right home appears.

Area YTD Median Price (Jan–Jun 2026) Source
Fort Worth $333,068 GFWAR June 2026 Report
Tarrant County $350,528 GFWAR June 2026 Report
Denton County $434,748 GFWAR June 2026 Report

Those price differences matter more than most buyers realize. If you're pre-approved based on a rough estimate of what you "think" you can afford, you may be touring homes in Denton County when your budget actually fits Fort Worth or Burleson. Pre-approval gives you a real number, not a guess. If you're still working through what those numbers mean for your situation, my post on how much house you can really afford in North Texas is a good place to start.

Pre-Qualification vs. Pre-Approval: The Difference That Wins (or Loses) Deals

These two terms get used interchangeably, but they are not the same thing, and sellers in North Texas know the difference.

Pre-qualification is informal. A lender takes your self-reported income, debts, and assets and gives you a ballpark number. No verification, no credit pull (or only a soft pull). It takes fifteen minutes and means almost nothing to a listing agent reviewing competing offers.

Pre-approval is a conditional commitment. The lender has pulled your credit, verified your income documents (W-2s, tax returns, pay stubs), reviewed your assets, and run your file through underwriting guidelines. You get a letter with a specific loan amount. That letter tells the seller's agent: this buyer has been vetted.

According to NAR's 2024 Profile of Home Buyers and Sellers, 4% of successful homebuyers had at least one mortgage application rejected before ultimately closing, with debt-to-income ratio problems cited in 40% of those cases and low credit scores in 23%. Pre-approval is how you find those problems before you're under contract and have already paid for inspections.

In a market where homes can go under contract in under a month, discovering a financing issue after you've written an offer is an expensive problem. You could lose your option fee, and depending on contract timing, potentially your earnest money too. Pre-approval shifts that risk to the beginning of the process, when the stakes are zero.

How Pre-Approval Fits the Texas Homebuying Process

Texas has a specific transaction sequence that makes pre-approval even more important than in some other states, and it's worth understanding before you start touring.

The TREC Contract and Buyer Approval Deadline

When you write an offer in Texas using the standard TREC One to Four Family Residential Contract, buyers using financing typically attach the Third Party Financing Addendum. That addendum sets a "Buyer Approval" deadline, a specific date by which you must obtain full loan approval. If you're starting the pre-approval process after you go under contract, you're already behind. Buyers who come in pre-approved have a much easier time meeting that deadline and are far less likely to need extensions that can frustrate sellers or put the contract at risk.

The Seller's Disclosure and Why Speed Matters

Under Texas Property Code § 5.008, sellers of most previously occupied single-family homes must provide a written Seller's Disclosure Notice detailing known material facts and property condition. As of July 1, 2026, TREC has mandatory updated forms in effect, including a revised Seller's Disclosure Notice and a new Water Notice (TREC No. 61-0). Always confirm the latest required forms directly with TREC or your agent.

That disclosure often reveals things worth knowing: foundation history, prior flooding, roof age, mechanical systems. A pre-approved buyer can review that disclosure and quickly ask their lender whether any issues would affect underwriting. A buyer who hasn't started the loan process yet has to pause, figure out financing, and then circle back. In a market where a well-priced home in Cleburne, Burleson, or Joshua can attract multiple buyers, that delay can cost you the house.

The Title Company's Role in Your Closing Timeline

Texas is a title company closing state. Your title company acts as escrow agent, holds your earnest money, orders the title commitment, coordinates with your lender to prepare the Closing Disclosure and loan documents, conducts the signing, and records the deed with the county clerk (Tarrant County Clerk, in most Fort Worth transactions).

Here's the key: the title company cannot finalize the closing until the lender delivers clear-to-close instructions. Pre-approval shortens that path because a significant portion of the underwriting work is done before you ever write an offer. Buyers who walk in fully pre-approved tend to have smoother, faster closings. That matters to sellers, and it matters to you.

For a broader look at what the local buying process involves in Tarrant and Johnson Counties, my guide on buying a home in Johnson and Tarrant County in 2026 walks through the full sequence.

What Listing Agents in North Texas Actually Expect

Texas law doesn't require you to attach a pre-approval letter to an offer. But in practice, listing agents across Fort Worth, Weatherford, Aledo, and the surrounding communities expect one. In competitive price ranges, offers without a current lender letter are often set aside in favor of similarly priced offers from pre-approved buyers. I've seen it happen. It's not a technicality. It's a real competitive disadvantage.

Your specific situation, your price range, your target neighborhoods, and your timeline all shape how much this matters. That's exactly the kind of question I walk buyers through before we ever schedule a showing.


If you've found this helpful, I'd appreciate you taking a moment to share your experience. You can read what other buyers and sellers have said on Google, Zillow, or Realtor.com.

Frequently Asked Questions

Do I really need a mortgage pre-approval before I start touring homes in Fort Worth?

Yes, and not just as a formality. In Fort Worth's 2026 market, homes in attractive price ranges still receive multiple offers and go under contract in weeks. Listing agents routinely expect a current pre-approval letter with any serious offer, and touring without one means you're not actually ready to buy, even if you find the right home tomorrow.

What's the difference between pre-qualification and pre-approval when buying a house in Texas?

Pre-qualification is an informal estimate based on self-reported information and carries little weight with sellers. Pre-approval involves verified income documents, a credit pull, and a conditional commitment from the lender for a specific loan amount. In North Texas, sellers and their agents treat full pre-approval as significantly stronger evidence that a buyer can actually close.

Will a seller in Fort Worth even look at my offer if I don't include a pre-approval letter?

They might glance at it, but in competitive price ranges they probably won't take it seriously. North Texas listing agents commonly require or strongly prefer a current lender pre-approval letter to consider an offer. An offer at the same price from a pre-approved buyer will almost always be chosen over one without documentation of financing.

How long does a pre-approval letter stay valid in North Texas before I need to update it?

Most lenders issue pre-approval letters that are valid for 60 to 90 days, though this varies by lender and loan type. If your search extends beyond that window, you'll need to refresh it, which typically means updated pay stubs and a credit review. Confirm the specific expiration with your lender, and don't let it lapse while you're actively touring.

If my pre-approval is denied, can I still buy a home in North Texas, and what should I fix first?

A denial is not the end of the road. According to NAR's 2024 Profile of Home Buyers and Sellers, the most common reasons for rejection are debt-to-income ratio issues (40%), low credit scores (23%), unverifiable income (12%), and insufficient reserves (12%). Each of those has a path forward. A good lender will tell you exactly what to address, and the earlier you find out, the more time you have to fix it before you're under contract on a home you love.

How fast do homes sell in Fort Worth right now, and how does pre-approval help me move quickly?

As of mid-2026, estimates from national portals suggest Fort Worth homes go pending in roughly 28 to 46 days depending on the data source, with some well-priced homes moving faster. Pre-approval means that when you find the right home, you can write a credible offer the same day, rather than scrambling to start the loan process after the fact.


Pre-approval isn't just a box to check. It's the step that makes every other step in the North Texas homebuying process faster, cleaner, and more competitive. If you're ready to get started, or just want to understand exactly what a lender will look at before you call one, reach out to me directly and I'll walk you through it.

About Jason Cech

Jason Cech is the Owner and Broker Associate of Texan Heritage Realty Group in Cleburne, Texas, with over 9 years of real estate experience helping families buy and sell across Johnson County, Fort Worth, and North Texas. A DFW Real Producers Top 500 Agent and multi-year top producer, he leads his team with a client-first approach built on integrity, tradition, and excellence.

Fathom Realty · 817-776-8319

Equal Housing Opportunity. Jason Cech, Broker Associate, Fathom Realty, licensed by the Texas Real Estate Commission (TREC). This article is general information only and is not legal, tax, or financial advice. Confirm your specific situation with your attorney, tax advisor, lender, or closing officer. Broker fees and commissions are fully negotiable and not set by law. TREC: Information About Brokerage Services | TREC: Consumer Protection Notice.

Aug. 12, 2026

Godley's New High School and Local Real Estate

How does a new high school affect home prices and buyer demand near Godley, TX?
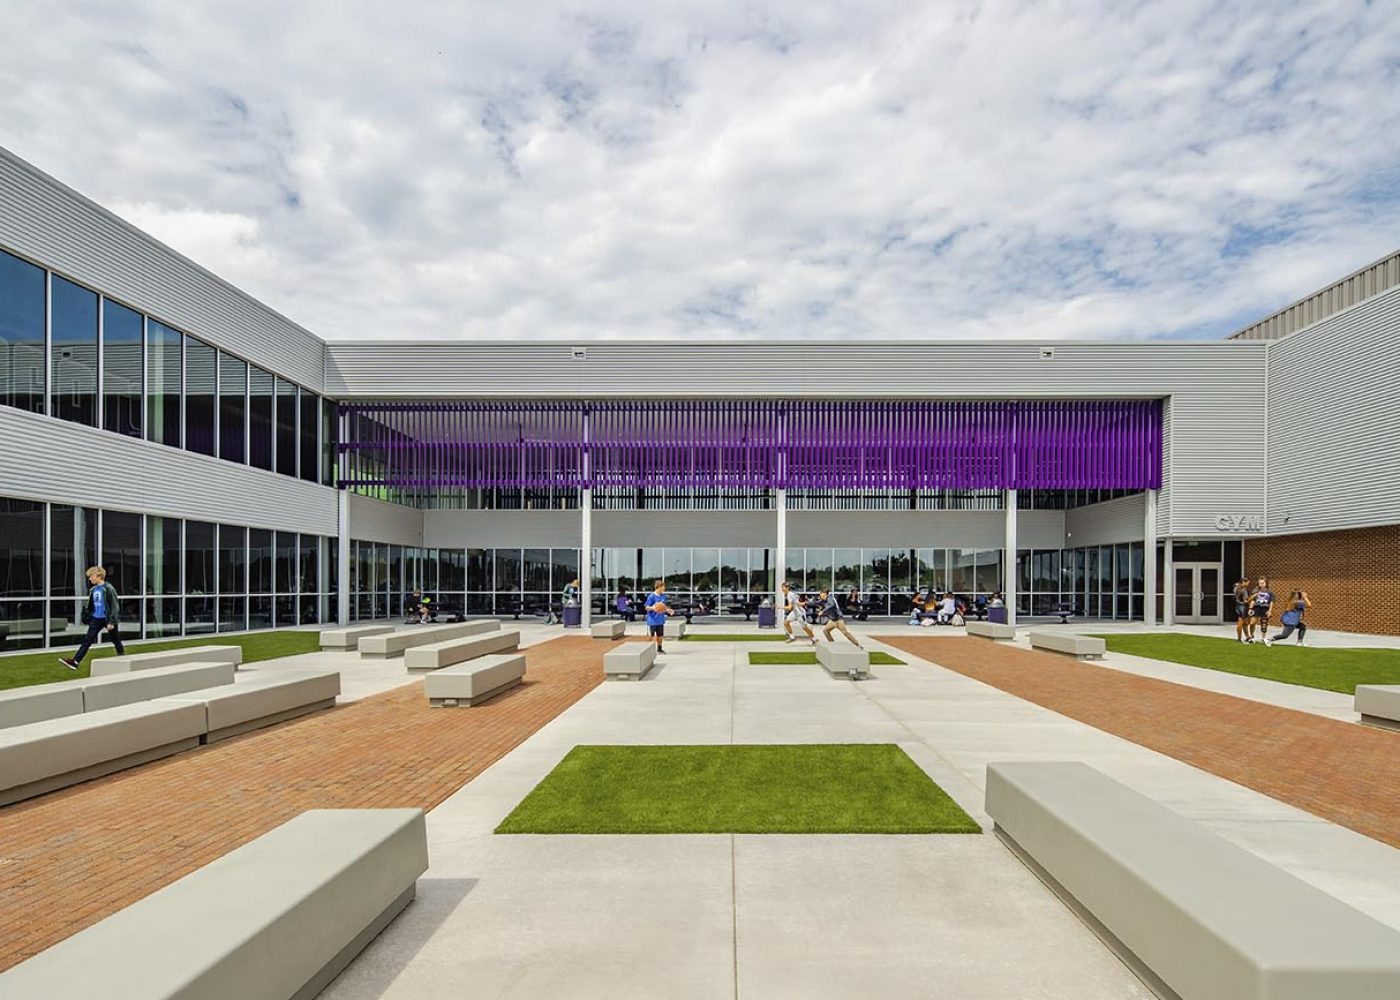
Godley High School, Phase 1 - Godley ISD

Godley ISD's first-ever high school opened in fall 2025, and it's changing the calculus for families considering a move to Johnson County. When a growing district completes its school path all the way through 12th grade, it removes one of the biggest hesitations buyers have about outer-ring communities. Homes in the Godley attendance zone are now drawing interest from buyers who previously looked past the area entirely, and that shift in demand is one of the most meaningful local real estate stories in the Fort Worth exurban belt right now.

Why the School Opening Is a Real Housing-Demand Story

Before fall 2025, families moving to Godley faced a real gap: the district didn't have a high school. That meant older kids were either attending school in a neighboring district or families were making a different relocation decision altogether. A complete K-12 district changes that conversation entirely.

I work with relocating families across Johnson County regularly, and the school-path question comes up on almost every buyer call. When I can tell a family that Godley ISD now has its own high school built for approximately 1,600 students, that's not a minor detail. It's a signal that the community has arrived at a new level of long-term infrastructure investment.

That kind of public investment matters to buyers because it reduces uncertainty. According to the National Association of Realtors, school quality and district completeness consistently rank among the top factors families weigh when choosing a neighborhood. A district with a new, purpose-built high school signals that local government is betting on continued growth, which is exactly what buyers in fast-growing suburban markets want to see before committing to a 30-year mortgage.

And Johnson County is genuinely in that growth corridor. The county sits squarely in the Fort Worth exurban ring, where U.S. Census Bureau population estimates have consistently shown faster-than-average growth for the broader DFW metro. Buyers priced out of central Fort Worth, Burleson, or Mansfield have been moving outward for years, and a complete school district is exactly the kind of amenity that anchors that trend in a specific ZIP code.

New Construction Absorption Gets a Boost

The most immediate effect isn't on resale homes. It's on new-construction subdivision absorption. Builders in and around Godley, Joshua, and Cleburne have been watching this school opening closely, and for good reason. When a district signals capacity for 1,600 high school students, it tells the market that the infrastructure is in place to support continued subdivision growth without the school system becoming a bottleneck.

If you're considering new construction in this corridor, it's worth understanding how the school opening fits into the broader picture. My post on whether you need a Realtor to buy new construction in North Texas walks through why having local representation matters, especially when builders are adjusting pricing in response to demand shifts like this one.

Resale Homes in the Attendance Zone

For existing homeowners near the new campus, the story is about positioning. Homes that sit clearly within the Godley ISD attendance zone now carry a marketing advantage they didn't have two years ago. That advantage is real, but it's also early. The school opened less than a year ago as of August 2026, so this is a post-opening, early-impact story, not a mature long-run trend with years of price data behind it.

What I tell sellers in this situation: the school opening is a legitimate talking point in your listing, but the number that matters most is still your specific home's condition, lot, and comparable sales. If you're thinking about listing, get a current market analysis before you assume appreciation has already baked in.

Factor Pre-Fall 2025 (No High School) Post-Fall 2025 (High School Open)
K-12 school path completeness Incomplete (no high school) Complete within Godley ISD
Buyer hesitation for families with older kids High Significantly reduced
New-construction subdivision appeal Limited by school-path gap Strengthened by 1,600-student capacity campus
Competing districts (Joshua, Cleburne) advantage Stronger relative position More level playing field
Long-term public investment signal Absent at high school level Present and visible to buyers

What Usually Follows a New High School in a Growth Market

A new high school doesn't exist in a vacuum. In North Texas growth corridors, a major school campus tends to pull other amenities behind it. That's not a guarantee, but it's a pattern I've watched play out in communities across Johnson County and the broader Fort Worth exurban belt.

Athletics facilities and event venues draw families to the area on weekends, which supports local retail and restaurants. Subdivisions that can market proximity to school athletic events, performing arts, and extracurriculars have a softer selling point that still moves buyers, especially families with middle schoolers who are already thinking about the high school years.

The Greater Fort Worth Association of Realtors and the broader DFW market data have consistently shown that outer-ring communities with improving amenity profiles close the price gap with more established suburbs over time. Godley is early in that trajectory, which is part of what makes it interesting for buyers who want to get in ahead of the curve.

For context on what's happening across Johnson County more broadly, my earlier breakdown of what buyers are asking about the Johnson County real estate market covers the demand trends that set the stage for why a school opening here carries more weight than it might in a slower-growth county.

How Far Is Godley from Fort Worth?

Godley sits roughly 30 miles southwest of downtown Fort Worth, which puts it in the commuter-viable outer ring for buyers working in Fort Worth, Burleson, or Cleburne. That distance matters for two reasons. First, it means Godley competes directly with Joshua and Cleburne for buyers who want more land, newer construction, and lower price points than closer-in suburbs offer. Second, a complete school district removes one of the last reasons a commuting family would choose a neighboring town over Godley specifically.

The Texas Department of Transportation has ongoing projects across the southwest Fort Worth corridor that affect drive times to and from Godley, so if you're evaluating a specific address, it's worth checking current highway conditions and planned improvements before making a commute-based decision.

A Note on Property Taxes and Appraised Value

One thing I want to flag for buyers considering Godley: in Texas, the Texas Comptroller's property tax system separates market value from taxable appraised value. The local appraisal district sets the appraised value used by taxing units, and that value can lag behind a fast-moving market. If the school opening accelerates appreciation in specific subdivisions, your purchase price and your first-year tax bill may reflect different numbers. Verify with the Johnson County Appraisal District before you close, and factor that into your monthly payment projections with your lender.

For sellers, a school-driven appreciation story is worth understanding in terms of both market value and what the appraisal district may do at the next reappraisal cycle. Your net proceeds depend on your actual sale price, not on what the CAD currently has on file.

What Buyers and Sellers Should Do Right Now

If you're a buyer looking at Godley, the window to get in front of this trend is open, but it won't stay that way indefinitely. The school opened less than a year ago, and the full demand effect typically takes 12 to 24 months to fully price into comparable sales. That's not a guarantee of appreciation, but it does mean the market hasn't fully repriced yet.

If you're a seller in the Godley attendance zone, this is a legitimate demand driver you can speak to in your listing. But price it right from the start. A school opening brings more buyers to the table; it doesn't override the fundamentals of condition, location within the zone, and competitive pricing. Make decisions based on your actual comparable sales data, not on what you hope the trend will add.

For either side of the transaction, if you're selling an existing home in Texas, the Texas Seller's Disclosure Notice is required for most single-family resale transactions. The school opening itself isn't a disclosure item, but any known property condition issues are. Work with your agent to make sure that form is complete and accurate before you go under contract.

Your specific situation, whether you're buying new construction, a resale, or preparing to list, is going to have details that a general market overview can't capture. That's exactly the kind of conversation I have with clients before we start the process. Get your free home valuation or start your Godley-area home search here.

I'd love to hear what other clients have experienced working with our team. You can read reviews on Google, Zillow, or Realtor.com.

Frequently Asked Questions

How does a new high school affect home prices near Godley, TX?

A new high school removes one of the biggest hesitations families have about buying in an outer-ring community: an incomplete school path. In fast-growing suburban markets, that kind of public infrastructure investment tends to increase buyer confidence and broaden the pool of qualified buyers for nearby homes. The effect is real but early in Godley's case, since the school only opened in fall 2025, so watch comparable sales data closely rather than assuming appreciation has already fully priced in.

Is Godley ISD's new high school already changing buyer demand?

Yes, and it's most visible in new-construction interest. Families who previously bypassed Godley because the district didn't have a high school are now actively looking at subdivisions in the attendance zone. The school was built to serve approximately 1,600 students, which signals to buyers that the district is planning for continued growth, not just catching up to current enrollment.

Which neighborhoods are most affected by the new Godley high school?

The strongest effect is in subdivisions that fall clearly within the Godley ISD attendance zone, particularly newer communities with family-sized homes and new-construction inventory. Buyers who value proximity to school events, athletics, and extracurriculars will also weight location relative to the campus itself. If you're not sure which specific addresses fall in the zone, that's something I can verify with you directly before you make an offer.

Do homes near a new school sell faster in Johnson County?

In growing suburban markets, homes in a newly complete school district tend to attract a broader buyer pool, which can support faster absorption. Johnson County has been one of the faster-growing counties in the Fort Worth exurban ring, and the Godley school opening adds a new demand driver on top of that existing trend. Whether a specific home sells faster depends on pricing, condition, and how clearly it sits within the attendance zone.

What amenities usually follow a new high school in North Texas growth areas?

Athletics facilities, performing arts venues, and school-adjacent retail and dining tend to follow a new high school campus over a 3-to-5-year horizon in growing North Texas communities. These secondary amenities reinforce the area's appeal and can extend the initial demand effect beyond the school opening itself. Godley is early in that cycle, which is part of what makes the current window interesting for buyers who want to get in ahead of the full build-out.

How far is Godley from Fort Worth, and why does that matter for commuters?

Godley is roughly 30 miles southwest of downtown Fort Worth, placing it in the commuter-viable outer ring for workers in Fort Worth, Burleson, and Cleburne. That distance means Godley competes directly with neighboring communities for families who want more land and newer construction at lower price points. A complete K-12 school district removes one of the last reasons a commuting family would choose a neighboring town over Godley specifically.

About Jason Cech

Jason Cech is the Owner and Broker Associate of Texan Heritage Realty Group in Cleburne, Texas, with over 9 years of real estate experience helping families buy and sell across Johnson County, Fort Worth, and North Texas. A DFW Real Producers Top 500 Agent and multi-year top producer, he leads his team with a client-first approach built on integrity, tradition, and excellence.

Fathom Realty · 817-776-8319

This article is provided for general informational purposes only and does not constitute legal, tax, or financial advice. Market conditions, school attendance zones, and property tax appraisals are subject to change, confirm your specific numbers with your attorney, tax advisor, lender, or title company before making any transaction decision. Equal Housing Opportunity. Jason Cech, Broker Associate, Fathom Realty. Licensed by the Texas Real Estate Commission (TREC). TREC Information About Brokerage Services | TREC Consumer Protection Notice.
Aug. 11, 2026

How Much Does It Cost to Sell a House in Cleburne, Texas?

How Much Does It Cost to Sell a House in Cleburne, Texas?

If you're thinking about selling your home in Cleburne, one of the first questions you're probably asking is: How much is it actually going to cost me to sell?

Quick Answer

There isn't one percentage that accurately represents the cost of selling every home in Cleburne, Texas. A seller's expenses can include real estate brokerage fees, title-related expenses, prorated property taxes, negotiated buyer concessions, repairs, home preparation, and other transaction-specific costs.

The good news is that many of these expenses are paid from the seller's proceeds at closing rather than out of pocket beforehand.

The best way to determine what you'll actually walk away with isn't to rely on a generic percentage. It's to calculate a seller net estimate using your home's expected selling price, mortgage payoff, property taxes, and likely transaction expenses.

Here's how the major expenses typically break down.

What Costs Should a Cleburne Home Seller Expect?

1. Real Estate Brokerage Fees

Real estate brokerage compensation is negotiable and can vary depending on the services provided and the agreements involved in the transaction.

Sellers should discuss compensation, marketing services, and their options with their real estate professional before signing a listing agreement.

It's also important to understand that buyer-agent compensation is negotiable and should not simply be assumed to be a fixed cost of selling.

2. Title and Closing Expenses

Depending on the contract and negotiated terms, sellers may have title-related and closing expenses.

These can include items such as title insurance, escrow fees, document preparation, tax certificates, HOA-related documents when applicable, and other transaction-specific charges.

The actual amount depends on the property, sales price, title company, and terms negotiated in the contract.

3. Property Taxes

Texas property taxes are generally paid in arrears.

Because of this, sellers will typically see their portion of the year's property taxes prorated through the closing date.

This sometimes surprises sellers because the tax proration appears as a debit on the closing statement even though the current year's tax bill may not have been paid yet.

4. Buyer Closing-Cost Assistance

A buyer may ask the seller to contribute toward certain allowable buyer expenses.

Whether agreeing to that request makes sense depends on the offer as a whole.

For example, an offer at a higher price that includes a seller contribution isn't necessarily better or worse than a lower offer without one. We need to evaluate the seller's estimated net proceeds, financing, appraisal considerations, contingencies, and overall strength of the offer.

5. Repairs

Repairs are one of the most unpredictable potential expenses.

Some homes sell with little or no repair negotiation. Others may require repairs before listing or result in repair requests after the buyer's inspection.

Common issues we encounter in North Texas transactions can include:

  • Roof condition

  • HVAC systems

  • Plumbing

  • Electrical issues

  • Foundation concerns

  • Wood-destroying insects

  • Septic systems

  • Water wells

  • Deferred maintenance

That doesn't mean sellers should automatically repair everything before putting a house on the market.

Sometimes making a repair provides a good return. Sometimes adjusting the price or negotiating after an inspection makes more financial sense.

6. Preparing the Home for Sale

Depending on the property's condition, sellers may also choose to spend money before listing.

That might include professional cleaning, landscaping, paint touch-ups, junk removal, minor repairs, or other improvements.

The key is determining which improvements are likely to help the home sell and which ones probably won't return the money spent.

We'd rather see a seller spend $1,000 strategically than spend $10,000 fixing things buyers wouldn't have cared about.

Example: Selling a $350,000 Home in Cleburne

Consider a hypothetical homeowner selling a Cleburne home for $350,000.

Assume the homeowner still owes approximately $200,000 on the mortgage.

Their starting equity would appear to be:

$350,000 sale price – $200,000 mortgage payoff = $150,000

But $150,000 isn't necessarily what the seller receives at closing.

From that amount, we still need to account for applicable brokerage compensation, title and closing expenses, property-tax prorations, negotiated concessions, repairs or credits, and other transaction-specific expenses.

That's why we recommend calculating the seller's estimated proceeds before listing the property.

Knowing your probable net is often more useful than simply knowing what your home might sell for.

What Determines How Much You'll Walk Away With?

The biggest factors include:

  • Your final selling price

  • Your mortgage payoff

  • Property taxes

  • Brokerage compensation

  • Buyer concessions

  • Repairs or repair credits

  • HOA expenses, if applicable

  • Other liens or outstanding obligations attached to the property

  • Negotiated terms of the contract

Two homeowners selling identical $350,000 houses could walk away with very different amounts.

Should You Make Repairs Before Selling?

Not automatically.

This is an area where having someone familiar with the local market can save sellers money.

Before making major improvements, ask whether buyers in your price range and neighborhood are likely to pay enough additional money to justify the expense.

A dated kitchen doesn't necessarily need a $30,000 renovation.

An aging roof, however, could create financing or insurance problems that affect the buyer's ability to close.

Those are very different situations.

What If You Need to Sell Before Buying Your Next Home?

Your estimated proceeds become especially important when you're planning to use equity from your current home toward the purchase of another property.

Before shopping for the next house, it's helpful to understand:

  1. What your current home could reasonably sell for.

  2. Approximately how much you still owe.

  3. Your estimated selling expenses.

  4. Your likely net proceeds.

  5. How those proceeds affect your next purchase.

This allows you to make decisions based on numbers rather than assumptions.

Frequently Asked Questions

Do sellers pay all closing costs in Texas?

No. Buyers and sellers generally have their own transaction expenses, and some expenses can be negotiated as part of the contract.

Does the seller have to pay the buyer's agent?

Buyer-agent compensation is negotiable. The terms should be evaluated as part of the overall transaction rather than treated as an automatic fixed expense.

Can a seller pay some of the buyer's closing costs?

Yes, depending on the buyer's financing and other applicable limitations. Seller contributions are commonly negotiated as part of an offer.

Do I have to make repairs after an inspection?

Not necessarily. Inspection findings can lead to negotiations, but sellers aren't automatically required to agree to every repair requested by a buyer.

Can I sell my Cleburne home as-is?

Potentially, yes. Whether that's the best financial strategy depends on the condition of the property, buyer demand, financing considerations, and expected selling price.

How do I know what my home is worth?

A useful home-value analysis should consider recent comparable sales, competing properties, condition, location, acreage or lot characteristics, improvements, and current market conditions—not simply an automated online estimate.

The Bottom Line

If you're considering selling a house in Cleburne, the most important number isn't necessarily the listing price.

It's what you're likely to walk away with after the sale.

Before making a decision, ask for both an estimated market value and a seller net estimate.

At Texan Heritage Realty Group, we help homeowners throughout Cleburne, Johnson County, and the surrounding North Texas communities understand both sides of that equation.

If you're considering selling but aren't sure whether now is the right time, we can prepare a property-specific market analysis and estimated seller net so you can see the numbers before making a decision.

Visit Our Site Here!

Texan Heritage Realty Group | Fathom Realty
Serving Cleburne, Johnson County, and surrounding North Texas communities
texanheritage.com

March 9, 2026

Is the Housing Market About to Crash? Let’s Talk Facts.

📊 Housing Market Headlines vs Reality

Why the Market Isn’t Crashing (Despite What Social Media Says)

If you’ve spent even a few minutes scrolling social media lately, you’ve probably seen someone claiming:

💬 “The housing market is about to crash again like 2008.”

They usually point to things like:

⛽ Rising oil prices
🏦 Banking concerns
📉 Foreclosure headlines
🌎 Global economic news

But when we step back and look at the actual data, the picture is far different.

In fact, many indicators show the housing market remains remarkably stable, and there are even signs it could improve as we move further into 2026.


📉 Mortgage Rates Are Holding Steady

One of the most important numbers in housing is mortgage rates.

According to Mortgage News Daily, the average 30-year fixed mortgage rate remains under 6.25%.

That’s notable because oil prices recently spiked near $100 per barrel, which normally pressures rates upward.

Despite that pressure, rates have remained relatively stable, which continues to support buyer activity.


📊 A Key Economic Report Many Headlines Missed

A recent report on the U.S. labor market revealed something important.

📉 February Non-Farm Payrolls: –92,000 jobs

On top of that:

• December job growth was revised from +48,000 to –16,000
• That means two negative job reports within 90 days

While that might sound concerning, labor market cooling often helps bring mortgage rates down over time, which improves affordability for buyers.


🚨 Housing Market Rumors vs The Actual Facts

A lot of fear about the housing market right now is being driven by misleading information online.

Let’s look at some of the claims circulating — and what the data actually says.


⛽ Oil Prices

Oil prices have jumped roughly 50% in the past couple weeks, which can temporarily increase inflation concerns.

However, most economists believe this spike is tied to short-term geopolitical tensions, not long-term inflation.


🏦 Regional Banks

Some headlines claim banks are struggling.

The reality:

• Banks hold trillions in Federal Reserve reserves
• They have access to emergency liquidity facilities
• Lending standards are far stronger than before 2008

The financial system today is dramatically more stable than it was leading into the Great Financial Crisis.


🌏 Japan Selling U.S. Treasuries

You may have heard that Japan is dumping U.S. debt.

That claim is simply not accurate.

In reality:

📈 Japan increased its U.S. Treasury holdings
from $1.06 trillion in 2024
to $1.2 trillion in 2025

That’s actually above their six-year average.


📉 Foreclosures

Another claim floating around says foreclosures are up 32%.

The data shows the increase is closer to 14% year-over-year.

More importantly, the context matters.

Foreclosures During the Housing Crash

🏚️ 2008-2013: 14.5 million foreclosures

Compare That to Recent Years

📊 2017 — 676,000
📊 2018 — 624,000
📊 2025 — 367,460

Between 2014 and 2018, the U.S. averaged 713,000 foreclosures per year.

Today’s levels are nearly 50% lower than those averages.


⚠️ The Biggest Problem in Housing Right Now

The biggest challenge facing today’s housing market isn’t:

❌ Supply
❌ Demand
❌ Interest rates

It’s misinformation.

Many buyers and sellers are making decisions based on headlines and viral posts that simply don’t reflect what’s actually happening in the market.

Our role as real estate professionals is to help people cut through the noise and focus on the facts.


📈 What the Bond Market Is Telling Us

Mortgage rates are heavily influenced by the 10-year Treasury yield.

For months, the 10-year Treasury has been moving in a fairly tight range.

The Key Level

📊 4.20%

As long as the 10-year Treasury stays below that level, mortgage rates should remain relatively stable.

Right now, it’s hovering around 4.13%.

If the yield drops below 4.10%, mortgage rates could drift closer to 6.05–6.10%.


🏡 What We’re Seeing in the Real Estate Market

Despite the noise online, activity in the real market remains strong.

Here’s what we’re seeing:

✔ Long-time homeowners starting to move again
✔ Millennials entering the housing market
✔ Buyers gaining confidence
✔ More transactions happening compared to last year

In fact, purchase closings in February were up 166% compared to last year, and March activity is already looking strong.

The demand is still there.


⭐ Final Thoughts

The housing market isn’t repeating 2008.

Today’s market is built on:

✔ Strong homeowner equity
✔ Strict lending standards
✔ Low foreclosure levels
✔ Continued buyer demand

While headlines may say otherwise, the opportunities in this market remain very real.

The key is making decisions based on facts, not fear.


🤝 Thinking About Buying or Selling?

If you're considering making a move in Cleburne, Burleson, Fort Worth, or anywhere in Johnson or Tarrant County, our team is here to help you understand the market and make confident decisions.


Texan Heritage Realty Group
🏡 Serving North Texas Buyers & Sellers
📞 Call or Text: 817-776-8319
🌐 www.texan-heritage.com

Posted in Market Updates
Feb. 23, 2026

Step 4: Closing & Moving

🏡 Homeownership Simplified – Step 4: What Happens Before You Get the Keys in Johnson & Tarrant County?

You’ve made it — you’re about to close on your new home. Here’s what to expect before you get those keys in your hand.

What actually happens before closing day in Johnson or Tarrant County?
Before you get the keys, you’ll complete a final walkthrough, review your Closing Disclosure, sign loan documents, wire funds, and wait for the transaction to officially record. Once it records — you’re a homeowner.

It’s exciting. It’s nerve-wracking. And yes, there are still a few important steps before you pop the champagne. 🥂


🔎 Step 1: The Final Walkthrough

This typically happens 24–48 hours before closing.

The final walkthrough is your opportunity to confirm:

  • Agreed-upon repairs are complete

  • The home is in the same condition as when you made your offer

  • No new damage has occurred

  • Appliances that were included are still there

In Johnson & Tarrant County, we often see repair negotiations related to:

  • Roof adjustments after inspection

  • Foundation evaluations (common in North Texas soil)

  • HVAC servicing

  • Minor plumbing fixes

This is not a second inspection — it’s a confirmation.

If something isn’t right? We address it before closing. That’s part of our job at Texan Heritage Realty Group — protecting you all the way to the finish line.


💰 Step 2: Review Your Closing Disclosure Carefully

At least three days before closing, your lender will send your Closing Disclosure (CD).

This document outlines:

  • Final loan amount

  • Interest rate

  • Monthly payment

  • Closing costs

  • Cash required to close

And yes — you should review it carefully.

We always recommend buyers:

✔️ Compare it to your original Loan Estimate
✔️ Confirm your name and property address
✔️ Verify credits negotiated during inspections
✔️ Double-check your cash-to-close amount

Property taxes can vary significantly between Johnson County and Tarrant County, so make sure those prorations look correct.

If anything looks off, ask questions. That’s why you have a team.


🖊️ Step 3: Closing Day – What Actually Happens

Closing day usually takes about an hour.

Here’s what to expect:

  1. Bring a valid ID

  2. Confirm your wire transfer was sent (never trust emailed wiring instructions without verbal verification ⚠️)

  3. Sign your loan documents

  4. Sign title documents

You’ll sign more paperwork than you expect — but we promise, it’s normal.

In Texas, once documents are signed, the title company sends everything for funding and recording. After it officially records with the county, the home is legally yours.

That recording timeline can vary — sometimes it’s quick, sometimes it’s later in the afternoon. Patience is key.


🚫 What Not to Do Before Closing

This part matters more than people realize.

Until you close:

  • Don’t open new credit cards

  • Don’t finance furniture

  • Don’t change jobs

  • Don’t make large unexplained deposits

Yes, even buying a new sofa can affect final loan approval.

Your lender will re-verify your financial profile right before funding. Keep things steady.


🔑 Then Comes the Best Part

Once funding and recording are complete…

We call you.

And we hand over the keys. 🎉

This is the moment that makes the paperwork worth it. Whether you’re buying in Cleburne, Burleson, Fort Worth, or anywhere across Johnson & Tarrant County — it’s a big milestone.

And we celebrate it with you.


🏠 Why This Final Step Matters

Closing isn’t just paperwork. It’s protection.

The final walkthrough protects your investment.
The Closing Disclosure protects your finances.
Title review protects your ownership rights.

Buying a home is one of the largest financial decisions you’ll make. The final steps deserve attention — not shortcuts.

At Texan Heritage Realty Group, we walk our clients through this process carefully so nothing feels rushed or confusing.


📚 Missed the First Three Steps?

If you haven’t read:

  • Step 1: Preparing to Buy

  • Step 2: Touring & Offers

  • Step 3: Inspections & Appraisals

Head back and catch up. This series was built to simplify the process — one step at a time.

Next month, we shift gears to our Real Estate Market & Money Series, where we’ll break down local trends across Johnson and Tarrant County.


🎯 Ready to Start Your Buying Journey?

Whether you’re just starting or already under contract, we’re here to guide you.

📞 817.776.8319
📧 Ashley@texanheritage.com
🌐 texan-heritage.com

Texan Heritage Realty Group 🤠
Helping buyers across Johnson & Tarrant County move forward with confidence.

Feb. 21, 2026

Homeownership Simplified – Step 3: Inspections, Appraisals & What Happens After Your Offer Is Accepted

The deal’s not done yet — here’s what to expect next.

What happens after your offer is accepted in Johnson or Tarrant County?
You’ll go through inspections, negotiations, appraisal, and final underwriting — and yes, this is where surprises can happen.


Step 1: The Inspection 🛠️

In Texas, you’ll typically have an option period to conduct inspections.

Common issues we see locally:

  • Foundation movement

  • Drainage concerns

  • Aging roofs

  • HVAC performance

Not every issue is a deal-breaker.
But everything is negotiable.

We help you decide what’s reasonable to request — and what’s typical for homes in this area.


Step 2: The Appraisal 💰

Your lender orders this.

The appraiser determines whether the home supports the contract price.

If it comes in:

  • At value → smooth sailing

  • Above value → instant equity

  • Below value → negotiation time

We guide you through options calmly and strategically.


Step 3: Final Loan Approval

Your lender verifies:

  • Employment

  • Income

  • Debt

Big tip:
🚫 Don’t open new credit cards.
🚫 Don’t buy furniture yet.

Yes, it happens more than you’d think.


The Truth About This Phase

This is the most stressful part for buyers.
But it’s also temporary.

Having a team who manages deadlines, communicates clearly, and anticipates problems makes a big difference.

That’s our job at Texan Heritage Realty Group.


🔑 Questions About the Buying Process?

If you’re thinking about buying in Johnson or Tarrant County, let’s talk through your timeline.

📞 817.776.8319
📧 Ashley@texanheritage.com
🌐 texan-heritage.com

We’ll simplify it. Promise. 🤠

Feb. 19, 2026

Homeownership Simplified – Step 2: Touring Homes & Making a Strong Offer (Without Overpaying)

Your first showing? Don’t forget to check this.

What should you look for when touring homes in Johnson & Tarrant County — and how do you make a strong offer without overpaying?
Look beyond cosmetics, understand comparable sales, and structure your offer strategically based on the local market.


What to Look for During Showings 👀

When touring homes in Cleburne, Joshua, Burleson, or Fort Worth, focus on:

  • Roof age

  • Foundation signs (important in Texas soil)

  • HVAC condition

  • Neighborhood upkeep

  • Traffic noise at different times of day

Paint colors are easy to change. Foundations are not.


Understanding Market Value (Not Just List Price)

List price is marketing.
Market value is based on comparable recent sales.

We pull real comps in Johnson & Tarrant County so you know:

  • What similar homes actually sold for

  • How long they stayed on market

  • Whether price reductions happened

This keeps you from overpaying — or underbidding and losing.


Writing a Strong Offer 💪

A strong offer isn’t always the highest one.

It can include:

  • Flexible closing date

  • Clean option period

  • Strong earnest money

  • Clear financing terms

We structure offers to protect you while still being competitive.


The Emotional Part (Let’s Be Honest)

Buying a home is emotional.
But negotiations should not be.

That’s where we step in.


📍 Want a Strategy Before You Tour?

Let’s make sure you walk into showings confident — not guessing.

📞 817.776.8319
📧 Ashley@texanheritage.com
🌐 texan-heritage.com

Texan Heritage Realty Group

Feb. 17, 2026

Homeownership Simplified – Step 1: What You Need Before House Hunting in Johnson & Tarrant County

Before you scroll listings, here’s what really matters.

What do you actually need before buying a home in Johnson or Tarrant County?
Before house hunting, you need three things: a clear budget, a solid pre-approval, and a realistic understanding of today’s local market.


Step 1: Check Your Credit (Yes, It Matters 😅)

Before looking at homes in Cleburne, Burleson, or Fort Worth, your credit score helps determine:

  • Your interest rate

  • Your loan type

  • Your buying power

You don’t need perfect credit. But you do need to know where you stand.

At Texan Heritage Realty Group, we connect buyers with trusted local lenders who explain your numbers clearly — no confusing mortgage talk.


Step 2: Get Pre-Approved (Not Just Pre-Qualified)

There’s a big difference.

A pre-qualification is a conversation.
A pre-approval is paperwork reviewed by underwriting.

In Johnson & Tarrant County, sellers often won’t even consider an offer without a pre-approval letter. Especially in competitive price ranges. Also, be careful of sites that give you an instant approval after filling in your personal information. An in depth credit review takes time and multiple factors need to be considered.

And here’s the truth: the homes priced well in Burleson and South Fort Worth? They move fast.


Step 3: Set a Realistic Budget

Just because a lender approves you for $400,000 doesn’t mean you should spend it.

We help buyers think about:

  • Monthly comfort level

  • Property taxes (which vary across counties)

  • Insurance costs

  • Future resale value

Johnson County often offers more square footage for the price compared to parts of Tarrant County. That matters when planning long-term.


Common Mistake: Starting With Zillow 😬

Scrolling listings is fun.
But without a strategy, it leads to:

  • Falling in love with homes outside your budget

  • Missing new listings

  • Overlooking better neighborhoods

The smartest buyers prepare first — shop second.


🎯 Ready to Start Smart?

If buying in Johnson or Tarrant County is on your radar, let’s build a plan first.

📞 817.776.8319
📧 Ashley@texanheritage.com
🌐 texan-heritage.com

— Texan Heritage Realty Group 🤠

Feb. 14, 2026

Best Areas to Buy a Home in Johnson & Tarrant County (Based on How You Live)

Where should you buy in Johnson or Tarrant County?
It depends on your commute, lifestyle, and long-term plans — and that’s where local expertise matters most.

https://ap.rdcpix.com/527f6d797032b6cc2e0f6347f1175d3dl-m3832895576rd-w960_h720.jpg

If You Want Space 🌳

Look toward:

  • Cleburne outskirts

  • Joshua and surrounding communities

  • Newer developments with larger lots

Great for buyers who want breathing room and fewer HOA rules.

If You Want Convenience 🚗

South Fort Worth and Burleson offer:

  • Faster highway access

  • Shopping and dining nearby

  • Established neighborhoods with resale strength

If You Want New Construction 🏗️

Johnson County continues to grow with:

  • Builder incentives

  • Energy-efficient homes

  • Flexible layouts

But not all builders negotiate the same — we help you spot the difference.

Why Buyers Choose Texan Heritage Realty Group 🤠

We don’t just unlock doors. We:

  • Compare neighborhoods honestly

  • Protect your resale value

  • Negotiate aggressively but professionally

  • Keep the process calm (yes, really)

🎯 Ready to Find Your Place?

📞 817.776.8319
📧 Ashley@texanheritage.com
🌐 Texan-Heritage.com

Let’s find a home that fits your life — not just your loan approval.

Feb. 12, 2026

How Much Down Payment Do You Really Need to Buy a Home in Johnson & Tarrant County?

Do you really need 20% down to buy a home here?
Nope. Most buyers in Johnson & Tarrant County put down 3%–10%, depending on loan type and goals.

https://www.txpremiermortgage.com/wp-client_data/21100/4981/uploads/2019/08/1004949.png

Let’s Bust the Biggest Down Payment Myth 🚫

Many buyers delay purchasing because they think they’re “not ready.” In reality:

  • FHA loans can start at 3.5% down

  • Conventional loans often allow 3%–5% down

  • Some buyers qualify for down payment assistance

Homes in Johnson County often price lower than surrounding metro areas, making entry easier.

What Your Down Payment Actually Affects

Your down payment impacts:

  • Monthly payment

  • Interest rate

  • Whether PMI applies

  • Cash reserves after closing

At Texan Heritage Realty Group, we help you choose a strategy that fits your life — not just a lender’s spreadsheet.

Local Buyer Reality Check 🧮

In many Johnson County neighborhoods:

  • Entry-level homes still exist

  • New builds may offer lender incentives

  • Sellers may contribute to closing costs

That’s why local knowledge matters.

👉 Bottom Line:

Waiting to save more could cost you more if prices rise. Buying sooner (smartly) often wins.

📲 Let’s Run Your Numbers

Call 817.776.8319 or email Ashley@texanheritage.com
We’ll break it down without pressure — and without confusing jargon.

texan-heritage.com

Feb. 10, 2026

Buying a Home in Johnson & Tarrant County in 2026: What Local Buyers Need to Know

Buying a home in Johnson & Tarrant County in 2026—what should you expect?


If you’re buying in this area, expect steady prices, competitive listings, and opportunities if you’re prepared and working with a local team like Texan Heritage Realty Group.

https://us1-photo.nextdoor.com/post_photos/c2/14/c2149deb1b4e32a790dbc654fa418411

Why Buyers Are Watching Johnson & Tarrant County Closely

Buyers are moving just south and west of the Metroplex for one big reason: value. Areas like Cleburne, Burleson, and parts of Fort Worth still offer more home for your money than many Dallas suburbs.

Local insight from our team:

  • New construction continues to expand in Johnson County

  • Inventory is healthier than inner-city areas

  • Sellers are more open to negotiations than they were a few years ago

Translation? 🗣️ Buyers finally have some leverage again.

The Real Buying Process (No Sugarcoating 🍬)

Here’s what buying actually looks like in 2026:

  1. Get pre-approved (not just pre-qualified)

  2. Define must-haves vs. nice-to-haves

  3. Tour homes quickly — good ones don’t sit long

  4. Make a strong, clean offer

  5. Negotiate inspections strategically

At Texan Heritage Realty Group, we walk you through every step so there are no surprises at the closing table.

Common Buyer Mistakes We See (So You Can Avoid Them 😬)

  • Waiting too long to lock a rate

  • Skipping inspections to “win” a house

  • Focusing only on monthly payment instead of resale value

A smart buy today protects your future equity.

👉 Buyer Tip:

The right house at the right price matters more than timing the market perfectly.

✅ Ready to Buy Smart?

📞 817.776.8319
📧 Ashley@texanheritage.com
🌐 Texan-Heritage.com